19–25 October 2026 | Singapore Wholesale Fruit Market
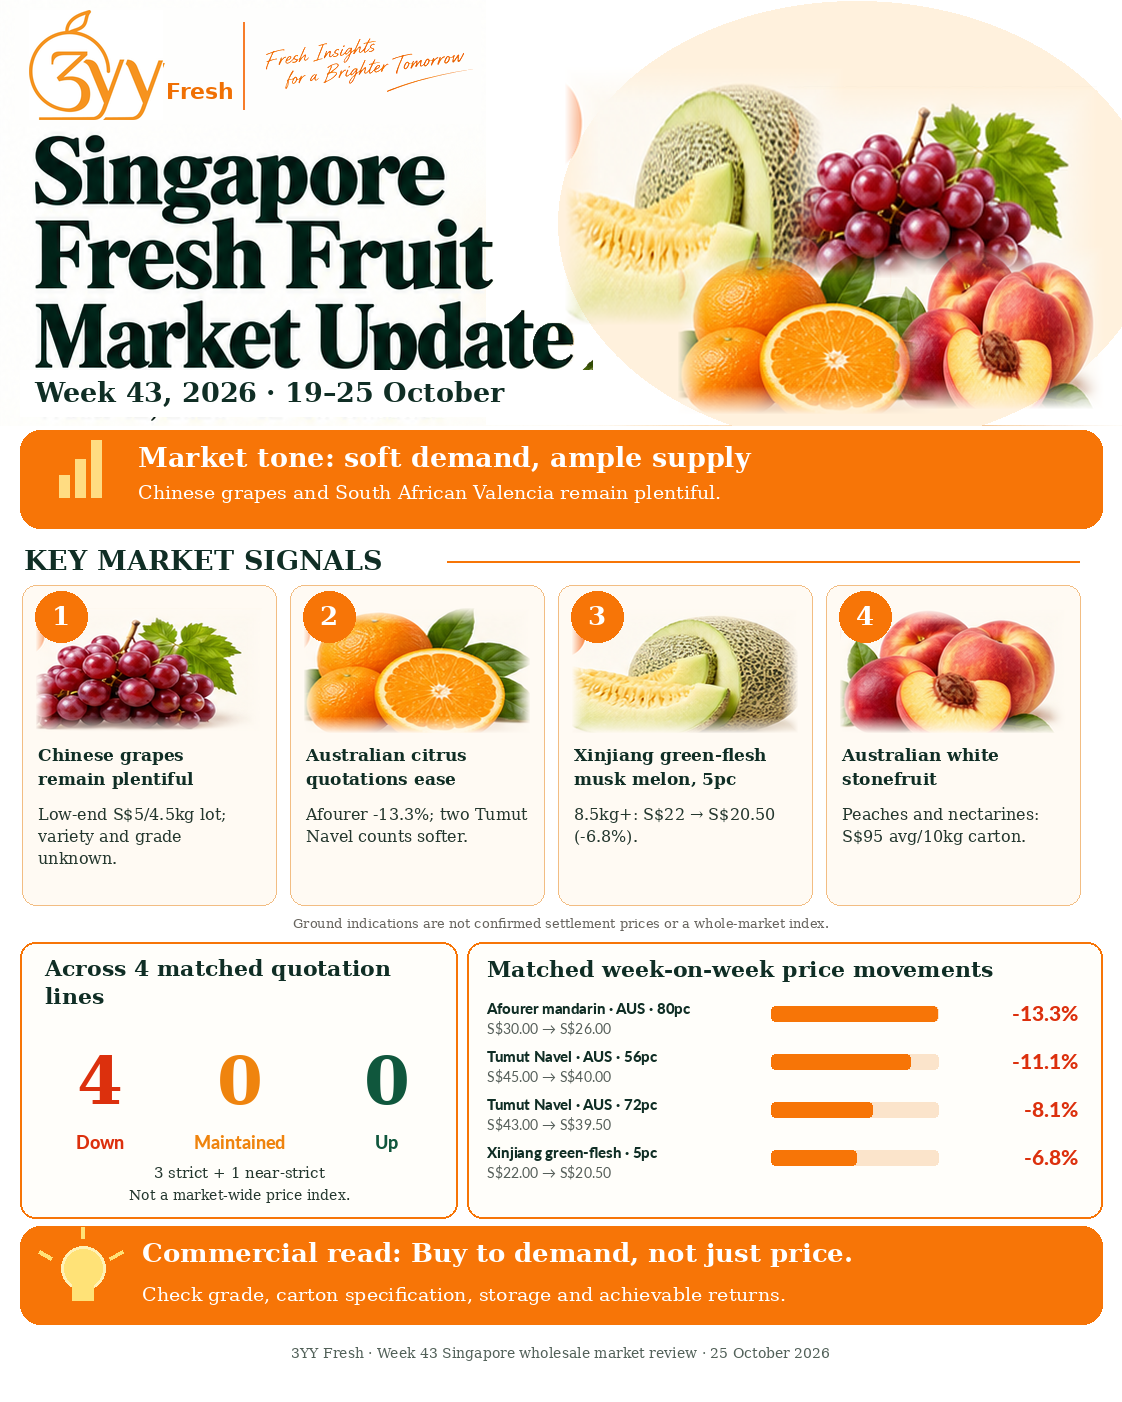
Singapore’s fresh-fruit wholesale market remained weak in Week 43. Buyers were cautious, with heavy availability reported in Chinese grapes and South African Valencia oranges. More Chinese lemons were circulating, while some Chinese Navel oranges were reportedly offered on consignment.
The four genuinely comparable Week 42-to-43 quotation lines all moved lower. That tells us something useful about those specifications, especially Australian citrus, but not the direction of every fruit category. An unusually cheap clearance offer is not the same thing as a confirmed, repeatable wholesale quotation.
Citrus: Australian Mandarins and Navels Lead the Price Declines
Australian Tumut Grove Afourer mandarins, 9kg/80pc, moved from S$30 to S$26 per carton, down 13.3%. This is a near-strict comparison because the two listings use “80s” and “80pc” wording.
Two Tumut Grove Late Lane Navel lines were strict matches. The 56pc carton eased from S$45 to S$40 (−11.1%). The 72pc carton averaged S$39.50 against S$43 in Week 42 (−8.1%), using two Week 43 quotations of S$40 and S$39.
South African Valencia supply, particularly Midknight, was described as excessive. A separate Mamba Valencia 72pc quotation was S$18, but no equivalent in-period Week 42 quotation was available to measure a weekly move. Ground checks also described some Chinese Navel oranges being offered on consignment, distinct from the Australian Navel products above.
Lemon availability reportedly increased, with modest price pressure. Without a like-for-like lemon quotation in either week's workbook, a precise weekly decline cannot be claimed.
Chinese Grapes: Heavy Supply, But the Lowest Price Needs Context
Chinese grapes continued to face intense supply pressure. One unusually low ground indication was approximately S$5 for a 4.5kg lot, or about S$1.11/kg. Its variety, grade, fruit condition and transaction terms were not supplied. This should not be interpreted as a standard wholesale price for all Chinese grapes.
Other Week 43 offers occupied different commercial positions: U.S. Autumn King green and Sweet Celebration red grapes at S$58 per 8.61kg carton; Adora black at S$66 per 8.16kg; Scarlotta red at S$63 per 8.16kg; and Peru Candy Dream black at S$48 per 4kg. Different origins, specifications and pack sizes make comparisons with an unidentified Chinese clearance lot unreliable.
Hami Melons: Broad Stability, One Matched Quotation Lower
Ground feedback described Hami or Chinese honey-melon prices as relatively stable after earlier clearance pressure. Within the strict matched data, however, China Xinjiang green-flesh musk melon, 8.5kg+/5pc, eased from S$22 to S$20.50, a decline of 6.8%.
A separate China 86King Hami melon, 11kg+/5pc, was quoted at S$16. The two packs are not equivalent, so this figure does not contradict the more general ground assessment or establish a like-for-like price gap.
Australian Stonefruit Enters the Picture
Australian 60mm white peaches and white nectarines in 10kg cartons were each quoted at S$94 and S$96, giving a Week 43 average of S$95 per carton for each category. These are Australian stonefruit offers consistent with its early summer-fruit season, not the start of a new U.S. peach harvest.
California peaches and nectarines were described in the report's dated industry references as finishing their season, with some late black-plum availability. Australian and U.S. stonefruit listings should not be treated as interchangeable products.
South African Mooncloud Royal Tioga cherries appeared at S$118 for 5kg/28mm+ and S$128 for 5kg/30mm+. These are current quotations, not week-on-week movements.
Berries, Pears and Other Listings
Zimbabwe Mamba regular blueberries, 125g × 12/14mm, were quoted at S$22, while Zimbabwe Berry Blossom 200g × 10/18mm++ Jumbo were S$34. Different brands, sizes and pack configurations prevent a strict comparison with earlier jumbo forward indications.
Australian Premiyum strawberries were offered at S$44 with the wording “250g / 15pc”. Week 42 used “250g × 15”. The pack descriptions are not sufficiently clear to claim a strict price fall.
China JP Fragrant Pear was quoted at S$18 for 7kg/XL 46pc and S$20.50 for 7kg/XXL 40pc. Other listings included Australian Edranol avocados at S$37.50–39 per 5kg carton and Vietnam Royal white-flesh dragonfruit at S$11–14, depending on count. These are current price references rather than proven weekly movements.
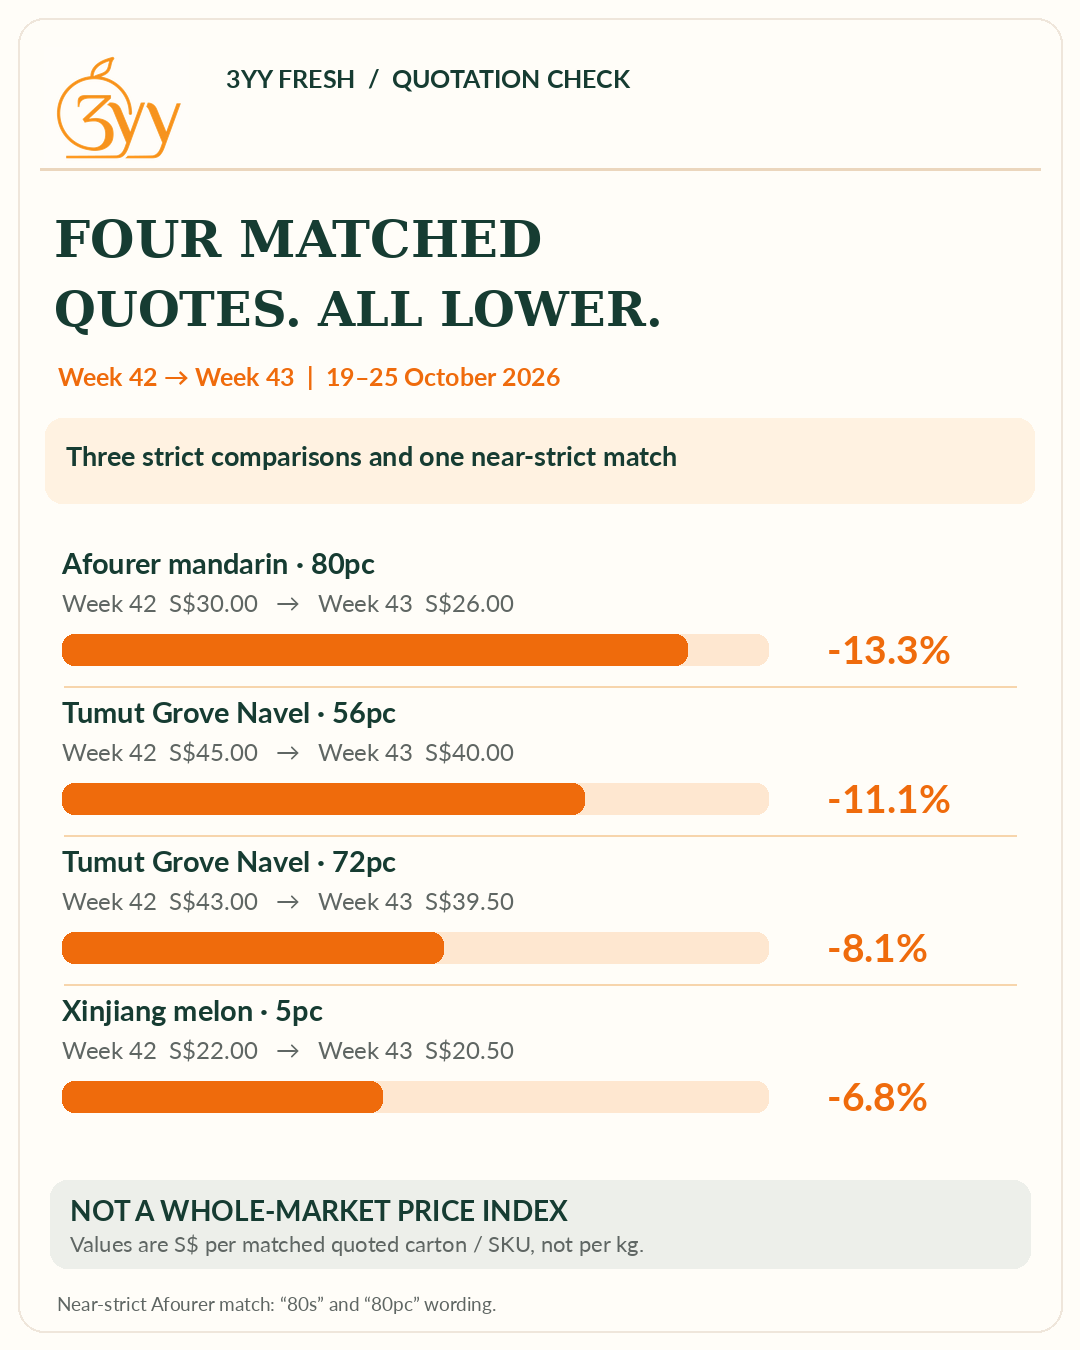
Four Matched Quotations, All Lower
The defensible Week 42-to-43 comparison consists of just four fruit specification lines:
- Tumut Grove Afourer mandarin, 9kg/80pc: S$30 → S$26 (−13.3%; near-strict wording match).
- Tumut Grove Late Lane Navel, 56pc: S$45 → S$40 (−11.1%; strict).
- Tumut Grove Late Lane Navel, 72pc: S$43 → S$39.50 (−8.1%; strict).
- Xinjiang green-flesh musk melon, 8.5kg+/5pc: S$22 → S$20.50 (−6.8%; strict).
All figures are S$ per quoted carton or pack, not per kilogram. These four observations are not a Singapore-wide fruit price index. Missing comparable quotations should never be interpreted as flat prices or an absent product.
What to Watch Next Week
The immediate question for importers and wholesalers is how reliably available fruit can move through the market. Consignment arrangements make final settlement returns uncertain; cold-room charges, shelf life, pack-out quality and working capital still matter.
In citrus and Chinese grapes, monitor clearance pressure alongside verified brand, count and carton details. In stonefruit, watch new Australian availability without confusing it with late U.S. listings. Retail promotions help explain consumer competition but do not reveal the retailer's buying cost or margins.
A low opening price can look attractive. A good buying decision still needs a confirmed route to sale.
For earlier context, see the Week 42 report and all previous market reports.
Methodology: 3YY's dated Week 43 market review, prepared 25 October 2026. Trader ground observations are indicative and not independently authenticated. Like-for-like quotation checks require matching origin, brand, variety, grade and pack; the Afourer wording match is near-strict. Retail prices are time-sensitive indications, not retailer procurement or margin estimates.